

On 1 November 2023, JD Sports Fashion disposed of its 78.2 per cent equity interest in GymNation Holding, including its subsidiary GymNation LLC. The seller recorded £34.2 million in total cash consideration. Later that month, GymNation announced who had led the buyout. Co-founders Loren Holland, Frank Afeaki and Anthony Martland, who were also part of the management team, became majority shareholders with backing from Tricap Investments and Ruya Partners. The people running the UAE gym business had taken control of its ownership. JD Sports Fashion’s 2024 accounts, note 12 GymNation’s buyout announcement
The disclosed buyers were the founders and managers leading the company. The announcement establishes a management buyout. It gives no basis for treating the deal as an ownership scheme for employees across the clubs. For a UAE management team considering a purchase from its current owner, this example lets you separate three decisions that often arrive together. Establish which shares the seller is transferring, who will control the business after closing and what the company will need to keep operating under the new ownership.
What management bought and what the seller disclosed
GymNation traces its first club to Al Quoz in Dubai in 2018. By the time of the buyout, management was dealing with an established gym operator with customers, locations and ongoing commitments. The seller and buyer described the transaction from different sides. JD Sports reported disposal of a 78.2 per cent equity interest. GymNation said the deal covered all equity held by JD Gyms and that the management team became majority shareholders. The seller’s entire stake was therefore different from the entire company. The disclosed numbers do not provide a complete ownership table after the deal. GymNation’s account of its first Dubai club JD Sports Fashion’s disposal note GymNation’s buyout announcement
The seller also reported £22.3 million in net cash received after deducting £11.9 million of cash and cash equivalents disposed of with the business. This reconciles to the £34.2 million consideration and answers a different question. It shows what the seller recorded on a net cash basis after accounting for the cash that left with the business. Neither number on its own tells the buyer what it will have available to pay operating bills or to open another club. For that, a team needs to see what sits inside the company on day one and what cash must be available in the weeks that follow. JD Sports Fashion’s disposal reconciliation
In a privately held UAE business, start by drawing the ownership before and after the transaction. Write the names of the entities whose shares are changing hands, the stake each buyer will receive and the decisions each can take. If managers are contributing different amounts of money or working in different roles, address what happens if one leaves the operating team. Put the financing beside that diagram. A shareholder, a lender and a manager may all have influence over the same business through different agreements. The ownership diagram helps show which questions need answers before anyone can describe who controls it.
What the financing partner added
Ruya Partners later said it provided a $25 million senior secured private credit facility in October 2023 that anchored the management buyout. In May 2026, it reported full repayment after GymNation secured a $100 million refinancing from HPS Investment Partners. GymNation described that later facility as backing its next phase of growth and confirmed Ruya’s exit as financing partner. The two facilities belong to different stages of the business. The later amount cannot be read as a price for the original shares, and Ruya’s original facility does not establish the full funding mix or each manager’s personal contribution. Ruya Partners’ account of the financing and repayment GymNation’s May 2026 financing announcement
For a team modelling its own transaction, build a list of cash sources and uses. Uses may include the payment to the seller, transaction expenses and money needed for working capital. Sources might include the managers’ capital, outside equity and committed borrowing. Identify which of those funds will be available at closing and which depend on conditions. If the buyer needs extra cash soon afterward, show where it could come from and whose approval is needed. A balanced table on the closing date tells you little about a gap several weeks later if no one has planned for it.
Then test a weaker operating month. In a hypothetical gym business, membership receipts might be lower than planned during a period when rent, payroll and equipment commitments still come due. Put those payments on the calendar alongside the expected borrowing costs and allow for work the club cannot postpone. If the business needs to close the gap by deferring a new opening, identify which commitments can actually be moved. This is a forecast of cash timing, so it needs inputs from the people who run the clubs and collect the money as well as those putting the deal together.
What operators know that still needs checking
The managers of a gym business can explain why a particular club struggles at one time of day, how quickly a broken machine can be replaced and which class schedules are hard to staff. That knowledge helps a buyer ask better questions. It also creates a risk of treating familiar arrangements as permanent. A manager may know the landlord and the equipment supplier, but should still verify which agreements need attention when ownership changes and what support came from the previous owner. Put someone in charge of confirming each answer and keeping a record of where it came from.
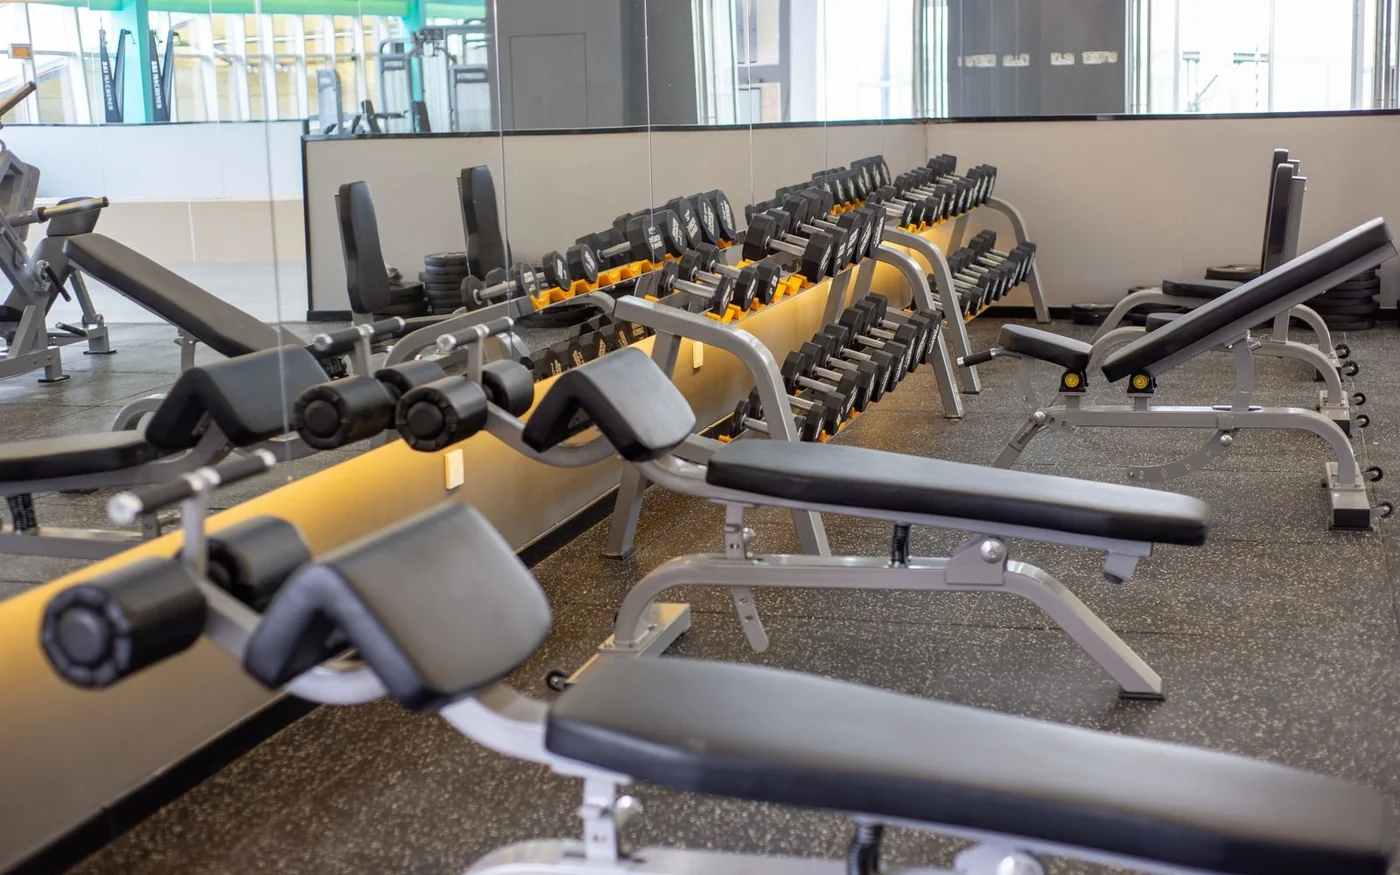
A GymNation Instagram reel from November 2023 shows a hoop workout inside a gym and gives a view of the customer-facing business around the time of the buyout.
For a hypothetical multi-site operator, pick one real transaction and follow it through the transition. A member signs up at one club and later wants to change the membership. The team needs to know which system holds the record, where the payment settles and who can approve the change after closing. If the seller provided any part of that process, establish who takes it over and when. Check the handover again from the point of view of a frontline worker who needs an answer while a member is standing at the desk. The acquisition may be settled while the operating transition still depends on an unresolved service or system.
Also ask what management would need to know if it were buying the business from strangers. Review how sales are measured, what customers can cancel and which equipment or fit-out costs are coming up. Compare what staff say with records from ordinary weeks. Where the two differ, work out whether the discrepancy reflects an unusual period, a reporting definition or an ongoing problem. Managers are well placed to explain the differences. A potential buyer still needs to understand how much those differences could cost.
Keep the clubs running while the deal closes
When a management team is negotiating a buyout, it is also responsible for a business that is still trading. Assign someone to run the transition and identify who keeps authority for ordinary operations during the deal. A club manager who needs to replace equipment should be able to tell which requests follow the usual approval route and which require a transaction decision. Give the same clarity to the staff who handle payroll, supplier payments and member queries. A team can rehearse the first day by walking through the transactions it cannot afford to interrupt.
Make communication specific to the recipient. An employee needs to know who manages them and what changes in the way they work. A customer needs to know how to use the service and where to get help. A landlord or supplier may need confirmation of the contracting entity or a named contact for invoices. Share those facts when they can be confirmed. When an issue is still open, tell the people affected who is responsible for resolving it and when they should expect a further update.
A buyout can change management’s responsibilities even when the operating team stays in place. A director who previously put a budget forward to the former owner may now have to weigh that spending against the obligations of the buyers and financing partners. Prepare a short list of decisions the team will revisit in the first quarter. If an expansion project competes for cash with equipment replacement at an existing club, show the timing and consequences of both choices. Agree what can be decided within the business and what must go back to the owners or financing parties under the arrangements in place.
Decide how the buyers will work together
Several managers can agree that they want to buy the company and still have different plans for what happens afterward. One may want to open more sites. Another may want to strengthen operations at the existing clubs first. Ask each buyer what outcome they are committing to, what time they can devote to the work and what would make them reconsider. Then discuss a decision where those views would produce different budgets. The discussion can reveal what needs to be settled before the managers take on a shared financial commitment.
Choose who will prepare the first operating review and who will challenge its assumptions. Someone who led the acquisition may have spent months making the case for it. A club leader who was less involved can explain what the forecast means for staffing, equipment and members. Give both a way to put difficult information in front of the owners early, while there is time to respond.
What to have in hand before making an offer
Begin with the seller’s stake and a clear picture of who would own and control the business. Ask which people on the management team will be buyers and which will continue in their operating roles. If the team wants broader employee participation, design that as its own decision and establish what employees would receive, when they would receive it and what commitments they would be taking on. The announced GymNation deal gives an example of managers buying control. Any wider scheme would call for separate evidence.
Bring the ownership plan, sources and uses of funds, operating forecast and first-day handover into the same review. Each should tell the same story about what the team can afford and who has authority. If the plan assumes an early expansion, check whether the operating team can pay for it without starving existing sites of maintenance or staffing. If it depends on support from the seller after closing, make sure that support appears in the transition plan with an owner and a date.
The GymNation transaction is unusually readable because the seller, buyer and financing partner each disclosed a different part. Together they show what changed hands, who led the buyout and one source of the money that supported it. A UAE management team can use those same three questions to scrutinise its own offer, then add the one its customers and staff will feel first. Can the business still deliver on the day after the ownership changes?
Comments (0)
No comments yet. Be the first!